


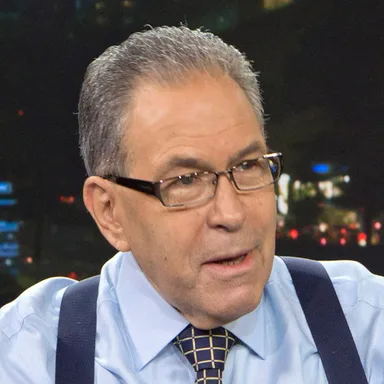
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Frank Korzekwinski
Transcript
Automated transcript · uncorrectedGood morning. This is Mike Stola for the Solar Real Estate Report twenty twenty six. New mayor, lots of new legislation, rent freezes, all these new problems that are in the market. But is there money for real estate? According to my guest today, there’s definitely money for real estate, but you have to be careful in what you do. I’m fortunate
to have my friend Frank cor Corzokwinski, who is the senior executive vice president in charge of real estate at Flushing Bank. Thanks for being here.
Thank you, Mike. Happy to be back again.
Okay, would you tell me first of all, what’s happening with a Flushing Bank in Ocean First Bank. I think it’s an interesting thing.
Well, certainly, at the end of December we entered do an agreement with Ocean First, and Ocean First will be acquiring a Flushing Bank, and the combined institutions will end up ultimately being about twenty three billion dollars in assets, a well capitalized financial institution. We estimate our Tier one capital to be in excess of thirteen percent strong reserves.
And one of the most notable parts of the transaction was Warburg Pinkis, which is an investment firm known for its quality investments, joined into the transaction and invested two hundred and twenty five million dollars into the deal. So it has given us a tremendous street credibility, and right now we are in the process of building a plan
of action to merge it or combine it two institutions sometime in the near future, and we’re just waiting shareholder approval as well as a regulatory approval.
I think you said it’ll be a twenty three billion dollars.
Twenty three billion dollars, seventy one branches with coverage from Washington, DC up to Boston. So we’ve become a very substantial part of a very successful organization and we’re looking forward to making our contribution.
Okay, with regard to lending, what are you lending on now?
So our book of business has not changed much over the years. We are still a community based organization providing financing for residential properties, mixed use properties, various types of commercial properties that you find throughout your neighborhoods. We are doing apartment building lending, not so much on the rent stabilized buildings. At this point in the market, a lot
of what we’re doing is focused on free market rents right now, and particularly in the smaller loan transactions. Some of the larger deals that are free market based are a little bit outside of our reach. However, you know, with the combined entity coming down the road with Ocean First, we should be able to compete more aggressively on some
of the larger transactions.
Now you have also a position in the SBA loans.
Yes, that was a wonderful edition. We recently launched a nationwide SBA program. We do have some deals going on throughout the country, not as much as we do here in New York. We are a preferred SBA lender. That team is run by our senior executive vice president, Terry Kelly in the business banking area. She’s brought in the
team of experienced SBA lenders that she’s known for many, many years. It’s really been a critical part of our community banking focus. We’re able to provide especially financing to small businesses throughout our communities and other parts of the country that may not have been able to borrow from a bank without a guarantee from the SBA.
Let’s talk about the twenty nineteen Act and the Rent Act the ESTPA.
I believe it was, yeah that it was quite a game changer in the market. Certainly has put a damper on the owners of multi family apartment buildings that are under rent stabilization. The increases, as you’ve known, in the last five years, have been particularly challenging. They’ve made a number of changes to the abatement tax abatement programs that
they had available for owners to reinvest in their buildings. They’ve extended the period of time in which they could recapture their investment, and they’ve significantly limited the amount of investment that they can make into a building and still achieve a return over a period of time. So it’s really been a very difficult situation for building owners to
absorb these buildings. Many of them go back to pre World War Two. Some of the buildings in New York City they got eighteen hundreds in some places in the Lower East Side. And a multi family business is a capital intensive business. It needs money to be invested constantly.
If you can’t reinvest, you can’t maintain the building. In order to reinvest, you need some sort of return. So we’re sort of at odds as an industry with that particular act right now.
What about the new act that we’re talking about, the REST Act.
So the REST Act is interesting. It’s it’s called the Rent Emergency Stabilization Act Act. It’s in the State Senate right now and it’s up for debate this session. And what it does is attempts to enable local municipalities throughout the state to institute rent regulations on residential dwellings with fewer than six units. This was also part of the
Copor Law, but was was removed later on. These local municipalities were given additional flexibility to utilize public publicly available data to make determinations as to whether or not a housing emergency exists.
This is there’s no question in a housing emergency does exist.
Listen throughout the throughout the state. There there is a challenge. You know, we just do not have a supply sufficient supply of residential dwellings to meet the demand, that’s for sure.
So continue on on the REST.
So you know, the REST Act is really going to impact the owners of a two, three, four or five family building throughout the state.
Weren’t they protected before?
No, they were free market buildings, meaning you were able to charge a market rent for whatever you.
So right now, under rest, they’re not going to be able to charge market rent.
So under rest, if it gets past, if you have a three family house and you have two tenants in there, your apartments will be required to fall under rent regulation. So that means whatever the state ETPA or DCR allows per year as a as an annual increase, excuse me as an annual increase, that’s what you will be able
to charge. So in many cases recently.
How can an owner operate a building that way?
It’s it’s extremely difficult, and I think you know, if a dishwasher goes, if a sewer line gets backed up, these are very substantial expenses for someone who owns a two or three family house to have to bear without having an opportun unity to recapture that cost. One of the side effects that it’s going to have is it’s
going to make it very difficult for borrowers or investors in a two, three, four or five family house to obtain market rate financing. I think many financial and banking institutions are going to shy away from those transactions because they’re starting to see now under E S t PA the challenges that owners have under rent regulation. So what
does that do? That opens the door for less than scrupulous lenders or speculating and lenders to come in and charge market rates well and excess of what’s going on in the market today. That means it costs more for the homeowner to run the building even though they can’t collect enough rent to pay for the added cost of
the financing or the repairs.
So how do we live with this potential rent frees.
That’s a real difficult question to ask. I think expense management is the name of the game. You need to be on your game in terms of controlling your expenses. You’re going to have these peak seasons like we had this February with heat and oil consumption kind of getting out of control. I think you will continue to see
some consolidation in the industry. The days of an individual owner starting out with a sixteen or twenty family building are probably gone because you need size and scale in order to compete in this marketplace. So it’s going to be very difficult going forward unless there are some changes to some of the regulations.
Let’s what type of changes do you possibly see.
Well, I think there’s some discussions out there that there’s twenty five or maybe thirty thousand vacant apartments in New York City that are under rent regulation. The quickest way to solve that problem would be to provide some type of vehicle in which owners can invest in those twenty five thousand units to bring them onto market, bring them
up to the condition that people would expect to live in, and it would not take years and years to solve that problem. If you’re going to build a two hundred unit building, whether it’s in Bronx or Brooklyn, it could take three years just to get through the approval process and then you have eighteen to twenty four months to
develop couple.
Do you have the situation if it has more than ninety nine units, it has to be Union.
Oh yes, but there’s another one coming out in ninety some ninety five X or something like that, or new tax forty five X excuse me. So that’s going to make it much more appealing for less than one hundred units, but it’s still going to take a couple of years.
So if the average, if the average building is one hundred units, it could take twenty years to build twenty thousand units. If you create an incentive for these investors to make invest their own money into the building, giving them some sort of investment credit or allowance to come up to market. They can solve that problem in less
than a year.
What’s your thoughts about the construction market?
Very hot right now. Anywhere you see an old shopping center that suffering some vacancies, that’s kind of being leveled and being redeveloped into some form of live work kind of space where they’re shopping, some office and some residential dwellings.
Long Island is on fire. Any piece of land that they can find, particularly in a transit hub. They’re popping up forty to fifty units at a clip. You know, it’s a desirable area for banks. The returns are better than they are in stabilized properties. I think all systems ago and there is a movement out of New York
City into Westchester County, Connecticut, parts of New Jersey and Long Island, and just a tremendous demand. So I see that being a very attractive market.
So I think it’s very interesting with the Ocean First deal and the fact that you’ve been there so many years and you’re on the pulse. And I’d like to thank you for being here today and best of luck on the merger.
Thank you, Mike. Look forward to seeing again.
Sunday, March 8, 2026
Dr. Mehmet Oz
CMS Administrator
NY State Per Resident Has The Highest Expenditures For Medicaid By Far In The Country
General David Petraeus
Former CIA Director & Four-Star General
The Operational/Military Campaign Against Iran Is Very Impressive So Far
Shar Pourdanesh
The Iranian Regime Has Been Oppressing The Iranian People For 40 Years
Edward Price
The Fact That Liberal Economics And Liberal Politics Parted Ways Is Quite Fascinating
Carolyn Maloney
Former U.S. Representative from NY
Nothing Is More Important Than A Quality Of Rights For Women
Paul Zuber
SVP, NY Business Council
They Need To Fix The Climate Law In Albany, To Make Life More Affordable For New Yorkers
Steve Fulop
President & CEO, Partnership for NYC
Socialist Democrats Applying New Taxes, Scares Off Investments In The City
Nicole Malliotakis
U.S. Representative from New York
SCOTUS Stop Redistricting Case For The 11th Congressional District
David Paterson
Former Governor of New York
If Kristi Noem Had Told The Truth, She Might Still Be The DHS Secretary
Jesse Arm
Vice President of External Affairs, Manhattan Institute
Is The Median Democratic Voter Moving To The Left, Or Is The Party Being Pulled To The Left
Dr. Peter Michalos
WABC Medical Expert
Technology In Medicine Nowadays Could Assist In Calculating Life Expectancy
Steve Kates
Space and astronomy broadcaster (Dr. Sky)
Due To Budget Cuts Last Year, NASA Has Delayed The Return To The Lunar Surface
John Terrett
WABC Financial Analyst
Markets Experiencing High Volatility From The Outbreak Of Hostilities In The Middle East
Michael Stoler
Michael Stoler
Real Estate Expert
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
