


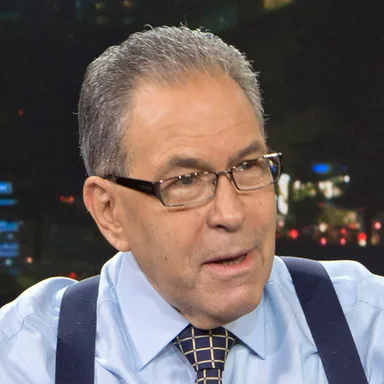
Michael Stoler Real Estate Expert
Interviews Joel Marcus of Marcus & Pollack
Transcript
Automated transcript · uncorrectedGood morning. This is Michael Stoller for the Stolar Report. This morning, I have the honor and pleasure of having Joel Marcus, the senior partner of Marcus and Pollock, a law firm whose principal areas of concentration include real estate tax review and litigation, tax surciority, commercial and residential tax exemptions and abatements, condemnation, tax planning, and other areas of
municipal and state law. In addition, he is a mensch and in addition, he’s a real estate expert in the fullth sense of the word. Thanks for being with me this morning.
Thank you, Michael.
So tell me what’s really going on.
For the first time, I have to be pessimistic. These are very scary times. You know. We’re in the property tax appeal business, and so we have access to real time income expenses. We have vacancies, we have rent roles, we have lease abstracts. We know what the problems are of our clients. We speak to them regularly. And I
have never seen a more scary time in real estate, except maybe the nineteen nineties when it was very bad. We have twenty percent systemic vacancy in the office market, and that’s looking like it’s going to increase, and it’s not that. It’s twenty percent and soon it will fill up.
The demand is not there, so there’s twenty percent. So any building that does better is taking some tenants away from another building, and there’s a flight to quality. So some of your older office buildings, they’re suffering at the expense of the high end, the high end. The big tenants can pay the price.
It’s the high end of your considering the new buildings and the A buildings, new.
A buildings, A plus plus buildings like four twenty five Park or Vanderbilt one Vanderbilt and some of the Hudson Yards building they’re getting it and for them their tenants, the rent is not an issue. They make so much money.
With regard to the Hudson Yards, what were the tax exemptions provided to owners, Well, there.
Were different tranches of it, but in the beginning, the first group that went in had campaigned only sixty percent of taxes and then it gets locked in and can’t go up more than three percent a year. So it was a very good tax abatement. Of course, they took a risk, they had to build a platform. Who knows
where they would work was interesting is that they did very well in the residential, they did very well in the office. They thought they would hit a home run in the retail, but that has proved not to be a successful story. They lost the name and Marcus as an anchor tenant, and there’s a real question there because
once you lose an anchor, there’s a danger of losing the inline stores. So they scrambling now to see how they’re going to reconfigure the situations.
Since we’re at eight hundred Third Avenue, what do you see on the third Avenue corridor that was always a B plus buildings or B buildings.
The largest availability of office spaces in the third Avenue carrid and it’s out of a favor from a lot of companies. Used to be a lot of law firms here. Most of the buildings here are showing twenty to thirty percent vacancy. There’s a lot of pressure on office rents, and these buildings don’t have the amenity space that some
of the newer buildings have. So we’re seeing that some buildings are taking out office space and converting it to amenity space, lounges and things of that nature. But the problem is is we give hybrid work. If you look at the castle system, which measures a number of people to go into the buildings, even a building that’s got
seventy five percent occupancy, only about thirty five to forty percent of the people who should be there are actually going through a turnstile. So we have a lot of people working remotely. And what that means is that when the tenants are renewing their leases, they’re opted to take less space and so they’re shrinking.
So why would you say today would be the landlord would provide a tenant with regard to everything and then also then put into the taxes.
Well, let me tell you. Taxes are probably going to be eighteen dollars a foot. Running the building is going to be twenty dollars a foot. You have tenant working concessions and leasing commissions and other one hundred and fifty dollars which adverortizes to fifteen dollars a foot.
I mean, so I’m at fifty three dollars before anything else is what you just said.
That’s right, And then so there’s nothing there for a profit. Actually, it’s nothing there for debt service. And that’s a real problem. Many of these buildings have a debt level that’s greater than the current market value, and if they want to roll it over when it comes due, they’re going to find that the interest rates are double what they were
a year ago. So this is a very scary time and I don’t see the market coming to the rescue. There’s not a lot of pent up demand.
What about the subject of conversion of office buildings, you know, BUS and C and D to residential.
We had the four to twenty one G program a number of years ago, and they converted a lot of very very old class C old buildings. But many of the office buildings downtown are not or for that matter, anywhere in the city, are not well suited for conversions.
Part of the problem is that they’re very dense buildings. You know, we have zoning rules that require a window in every room, so you have deep space that doesn’t suit well. And the few conversions that we’ve seen, the historic WR Grace building has huge hallways and a lot of lost space. The conversion that they did for two
seventy Park, I mean two seventy Church Street, which was a New York State building. I’ve been in some of those apartments. You walk through a whole long hallway after you’ve entered the apartment, just to get to the apartment, because they have these tortuous roots just so you can get to the windows. But these buildings don’t suit themselves
very well. And even in very large office buildings, the central core, the elevators, etc. The fire stairs are in the center, so you can’t even open up a courtyard. So we’ve looked at a couple of these conversions. Plus there is no program. We evaluated a proposed legislation. We did it at the request of the Real Estate Board
of New York, and we looked at it and they were going to offer a fifty percent tax abatement for a conversion, but they want forty fifty percent affordable rental and other aspects. And there was no promise that there would be significant tax relief other than the abatement, but the assessments were going to be very high based on
the course of conversion.
Whitey thoughts about the four twenty one a’s Are they going to come back? Oh? I mean, because many developers I know aren’t doing anything because if there aren’t any tax advantages, it’s no reason to go into it unless it’s a conduct.
Michael, You’re right. There was some talk of having a new four to twenty one A program, but those talks have gone nowhere. There’s nothing in legislation that’s been proposed. I think the governor and the state legislature don’t have the same idea, and I think unfortunately, the state legislature wants tremendous concessions on affordable housing and they just don’t
understand the economics of putting a building up and the rate of return that’s necessary.
So people have been coming to you. Do you think it’s a seller’s market or buyers market or you know it has the pendul Has a knife fallen enough?
No, I think it’s going to get worse. A knife hasn’t fallen, and there’s an old saying, never try to catch a falling knife. I think what we’re going to see is a number thing. One. For example, property taxes are going up tremendously, and if you take a look at the at the condominium market and you look at
the people that are going there, and they say, well, can you justify the values based on the rentals that people would pay, et cetera. And the answer is maybe you could, but people don’t make enough money to pay the maintenance and the real estate taxes. So they have to look at what I always say to my partner,
I said, what job do people have that can then allows them to own this condominium and pay these kinds of taxes. They’re very, very high. The city increased the total tax load eight point six percent overall from last year to this year. I mean, they see the storm clouds out there. You know, in addition to that, you’re
talking about commercial property. You know, you’re reading that the interest rates have gone up, that there’s a lack of liquidity, the ability to refinances is drying up. Today in the Wall Street Journal.
To write the article about the insurance companies basically saying that they’re walking away from the market because they’re scared. They have to be prudent, they have to be.
And they work on the numbers. And what did the city do. They lowered the capitalization rate for office buildings. It lowered it. Interest rates are higher, the risk greate is higher, the vacancy levels are higher, the amenity packages are greater. If you take a look at the at the stock price of some of the real estate companies,
they’ve gone down sixty percent in one year sixty percent. I mean, the market is telling something.
What’s going to happen with the red dividends.
They’re going to disappear these buildings. They don’t make enough when you are suffering a twenty percent vacancy and you have to struggle by the way, you know, not only do you have to take care of your debt service, very often you finance the course of the tenant work and the free rent. But the lenders are saying, you’re
already maxed out. We can’t give you any more money, so you have to go into pocket, you know, and put in some additional equity. Well, those are very tough times. I don’t think, you know, many buildings can do it.
We see buildings that are walking away from tenant deals because they’re either negative or they just don’t have the capital to go ahead with it.
So insummation, you know, as I used to say on my TV show with My Apple, the apple is not really bright in the eyes of Joel Marcus.
Correct, correct, the apple is not bright. And I would also say we’re walking into a perfect storm. I’ll tell you why, because in the nineteen nineties, where I saw buildings sell for half their tax sucsess value, which is shot.
We never saw that before. At least we had an active court system. We went to court. I tried one New York closet member of my famous case. We cut the taxes in half, and then we started rolling up and getting some big reductions and assessments. Right now, we’re not seeing that the courts are operating on a zoom basis.
There’s hundreds and hundreds of cases backed up waiting for a trial, so I don’t see any relief. And on top of that, who can make a decision. Well, we find that the senior people at the Tax Commission are retiring, sament the Department of Finance.
So Joe, I’m sorry that you were not positive, but you were realistic and I appreciate that. And to thank you for the Joel Marcus, senior partner of Marcus and Pollack.
Thank you very much. Michael
Sunday, May 7, 2023
Entire Assembly up for election with new district maps.
Bob Hugin Former Chairman, New Jersey Republican Party
Former governors discuss the state of the State.
Former NY Governors David Paterson & Andrew Cuomo
"No common sense in NYC politics"
John Chachas Investment Banker, Founder of Methuselah Advisors
Alternative to President Biden's nomination
Robert F. Kennedy Jr. U.S. Secretary of Health and Human Services
Battling the Fentynal scourge killing Americans.
DEA Special Agent in Charge Frank Tarantino
Water detected on a distant exoplanet.
Steve Kates Space and astronomy broadcaster (Dr. Sky)
Michael Stoler
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Robin Schneiderman
Michael Stoler Real Estate Expert
