


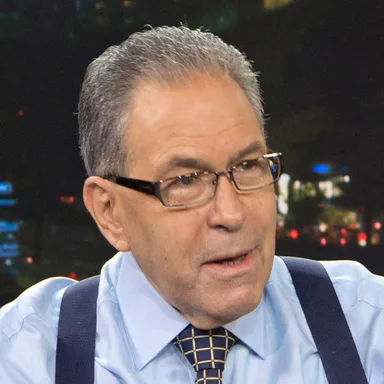
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: David Sterling
Michael Stoler
David Sterling, CEO of the insurance brokerage SterlingRisk, tells Michael Stoler that after five to eight years of rising premiums, New York City property insurance rates have been falling for the last year. He says competition among insurers that are now making money is driving the decline, while cyber insurance is getting more expensive as attacks grow more sophisticated.
Key takeaways
- Sterling said New York City commercial buildings without significant claims are seeing 5% to 20% premium reductions.
- He said insurers are starting to impose huge deductibles to avoid water damage claims from burst pipes.
- He said large Florida buildings have seen almost 50% price reductions over the last two years.
- He said California homes with high wildfire scores find insurance hard to get and very expensive.
- He advised people turning 65 to find an expert to walk them through their Medicare choices.
In their words
“capitalism is a beautiful thing. When there’s more than one company in a market and they’re both making money, they start competing with each other.”
“there is one claim that’s really hurting New York right now, and that’s water damage.”
“It’s very complex. And even a small misstep can cost you a lot.”
Quotes are word for word from the automated transcript, uncorrected; the summary and takeaways are editorial.
Transcript
Automated transcript · uncorrectedGood morning, this is Mike Stoller for the Stoller Real Estate Report. One area of coverage which is needed by individuals and businesses is the insurance coverage. What do you need? What are premiums? What’s happening in the market? It’s like a bouncing ball. It changes all the time. So today I have a expert in the insurance business. I have
David Sterling, who is the CEO of Sterling Rescue. one of the top 15 insurance brokers in the country. Thanks for being here, David.
Nice to be here. Thanks for having me, Michael.
Okay. So, David, let’s talk about the market today because, you know, many people remember that premiums were always up. And when we spoke the other day, you said premiums are down. So what’s happening?
Yeah, so we’ve gone through a transition. For five or eight years, we were having constantly increasing premiums, especially in the New York City area, and especially property insurance premiums. And for the last year, we’ve been seeing marked reductions.
If somebody has property insurance on a building in New York City, a commercial building, whether it’s a residential or office or retail building, They’re seeing, and they don’t have significant claims, they’re seeing anywhere from 5% to 20% reductions in premiums year over year.
What do you attribute this to?
So, you know, over the five to eight year period as rates were climbing, they were climbing in reaction to claims. So what happened is they climbed to a point where insurance companies were starting to make money And capitalism is a beautiful thing. When there’s more than one company in a market and they’re both making money, they start competing
with each other. And it’s that competition that’s driving down the rates.
So you’re also saying that all of the individuals who are listening to this report today are benefiting and getting lower rates. Is that correct?
Everybody who has business insurance for property insurance should be getting lower rates. And if they have bad claims, their increases will be much smaller than they would have been in the prior year.
Which companies have you seen that have been very active in this?
I would say all the big ones, Chubb, Hartford, Zurich, Travelers, CNA, Philly, Factory Mutual, all the big companies writing property insurance, Liberty Mutual, big companies writing property insurance, we’re seeing softening in their rates for good risks in New York.
What about claims?
So, you know, There’s two sides of claims. One question you might ask me about claims is how have the claims been? And so the claims haven’t been as bad the last few years, which is one of the reasons why we’re seeing this softening. And you’re asking, are they paying claims? Yes, all the big companies are paying claims
as they always have. For some clients, it’s a painful experience. For some clients, it’s not a painful experience. But there is one claim that’s really hurting New York right now, and that’s water damage. The older buildings have piping infrastructure that’s crumbling, and we’re seeing a lot of burst pipes even in the summer months. And the insurance companies are
starting to put huge deductibles on to avoid those water damage claims.
What about Florida?
So interesting, Florida, yeah, Florida, we’ve seen almost 50% price reductions over the last two years on large buildings in Florida. You know, think about the big condos or the big office towers. Since two years ago, the rate started going down in Florida due to this competition. And like I said, 50% reduction.
Okay, so what’s happening with regard to, let’s leave the property casualty for a second. Let’s talk about cyber policies and data centers. What’s happening with those type of coverage?
So in terms of cyber, we were seeing a softening in the market for the last few years, meaning it was easier and less expensive to buy cyber insurance. We’re seeing an uptick now, and I think that’s a reflection of we’ve been seeing an uptick in claim activity. The fees have gotten much more sophisticated. The attacks are getting
more sophisticated. And it’s that claim activity that’s driving some of the cost increases there. In terms of data centers, data centers are just very, very large property risks. And so, you know, those are really getting discounted today for the property insurance. And in terms of the cyber insurance for data centers, it’s getting a little bit more difficult because
we have seen significant increase in attacks over the last year.
Okay. With regard to specialty coverages, I remember the last time we had you on the show, you were talking that your company does a lot of specialty coverages. You want to talk about that?
So when we talk about specialty coverages, there’s a whole bunch of different areas. If somebody is buying or selling a company, we can ensure the representations and warranties so that the buyer, if they buy something and it doesn’t turn out to be what was represented, they don’t have to chase it. the seller. We sell specialty crime insurance policies,
employee theft, things like that. Bonds are another big specialty item we have. For example, when a developer is building a condominium and gets deposits We can bond those deposits so that the developer can use those deposits to finish construction or reduce his borrowing cost. So there’s a whole bunch of specialty products, very creative specialty products that we
have teams of people working on.
Okay. With regard to the coverages in California, especially after the Palisades fire, Are we seeing any premiums companies writing more coverage there, even though we’ve had big claims?
It’s really tough, Mike. Very, very slowly, some more companies are coming back into the market. California did make some insurance reforms, which drew some companies back. But the plain truth is they’ve developed a new rating system in California, and they call it a wildfire score. So wherever your home is, they take a look at what the wildfire
score is. And the wildfire score is based on the amount of underbrush and flammability around your home. And so if there is a likelihood that a wildfire could spread easily into your neighborhood and near your home, you’re going to get a high score. And the scores went from zero to 100. And anybody over 50 is going to
find it difficult to get insurance. And I’ve been looking at clients coming to me whose wildfire scores were in the 90s. And it’s not that it’s not available. It’s just very, very expensive. And, you know, the belief is that the municipalities, whether it be the villages, the city, the state, could do better in managing the the elements
that contribute to wildfires. And so these scores are a reflection of the fact that wherever you’re living with a high wildfire score, your local government is not doing what’s necessary to manage that risk. And as a result, you’re going to find it difficult to get insurance and it’s.
Going to be expensive. You know, with the coverages that individuals have to make on Medicare by December 7th, Do you have any suggestions of what people should be doing to get the best coverage?
You know, Mike, I have very strong feelings that none of us who turn 65 are really prepared to to make the decision as to what Medicare parts to opt for and what Medicare supplements to opt for. It’s really important you find a good advisor and somebody who really understands this and walks you through the decision. I know
I’m in the insurance business. And when I had to walk through that decision, I found an expert in this area to advise me. And it was really, really important. It’s very complex. And even a small misstep can cost you a lot. In other words, if you don’t opt for the coverage in the right timing, when you finally
do opt for it, it can be costing you a lot more than it should. So my advice is during this period, seek out a professional who understands this stuff and get the right advice.
And the last question on that topic really talks about long-term care coverage. You know, people took it and the premiums are insane and crazy. What you thought about?
When long-term care first came out, the insurance companies thought they, you know, had an amazing product. Everybody was buying it. It was very cheap. And that lasted until the claims started coming in. Once the claims started coming in, they realized they gave too broad coverage and too little premiums and so over time the premiums have gone up dramatically
and the coverage has been restricted I would advise anybody who can’t afford to be cared for in the event that they can’t care for themselves to buy the coverage. For high net worth people, I rarely advise them to get the coverage because the truth is the average amount of time you live, once you’re eligible to collect on
those policies, I think the last study I saw was six months. Meaning in order to collect, you have to not be able to do two of the five things that you need for living, like getting out of bed, getting dressed, getting showered, driving, walking, things like that. And if you have to be not able to do a
few of those things, and if you’re not able to do a few of those things, the average length of time you’re going to live is about six months. So for a high net worth individual who can afford that, I wouldn’t waste the money on premiums. But for someone who’s not high net worth, This is a critical coverage
to buy because it can buy you quality of life in the last few months of your life. So I think it’s important for most people to buy that coverage.
I’d like to thank you for your insight and information on the different coverages and what’s happening. I think everybody should spend time and evaluate what they’re doing and have professionals lead them. I’d like to thank... David Sterling, for being here today. See you next week.
Thank you, Mike.
Sunday, November 15, 2026
Rolling Back Regulations and Unleashing American Energy
Lee Zeldin EPA Administrator
Navigating Senate Rules to Advance Key Republican Priorities
Kevin Cramer U.S. Senator from North Dakota
Washington Must Maintain Pressure on Iran
General David Petraeus Former CIA Director & Four-Star General
America's Military Technology Priorities and the Race to Stay Ahead of China
Michael Dodd Assistant Secretary of War for Critical Technologies
Inside His Prison Years and His Views on Today's Democratic Party
Rod Blagojevich Former Governor of Illinois
Democrats Must Unite and Avoid Internal Infighting
David Paterson Former Governor of New York
New York’s Budget Surplus, Rainy Day Reserves and Fiscal Challenges
Tom DiNapoli New York State Comptroller
Fighting Human Trafficking, Promoting Faith and Reaching Hispanic Voters
Bob Unanue Former CEO of Goya Foods
The Legacy of Stanley Zabar and the Family Behind the Legendary New York Deli
Bill Wachtel Founding Partner, Wachtel Missry LLP
The Growing Financial Struggles Facing Small Business Owners
JT Foxx Entrepreneur & Investor
New Medical Breakthroughs Are Changing Alzheimer’s Diagnoses
Dr. Mason Pimsler Geriatrician, Lincoln Medical Center
Reversing the Effects of Aging and Maximizing Your Healthy Years
Dr. Peter Michalos WABC Medical Expert
The Future of Moon Exploration and Preparing Humans for a Mission to Mars
Steve Kates Space and astronomy broadcaster (Dr. Sky)
Congress Must Act Now to Protect Children from Online Dangers
Lynn Shaw Founder of Lynn's Warriors
Wall Street Weighs Nvidia Controversy Amid Growing AI Investments
John Terrett WABC Financial Analyst
Michael Stoler
The Stoler Report with Michael Stoler: David Schechtman
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
Michael Stoler Real Estate Expert
