


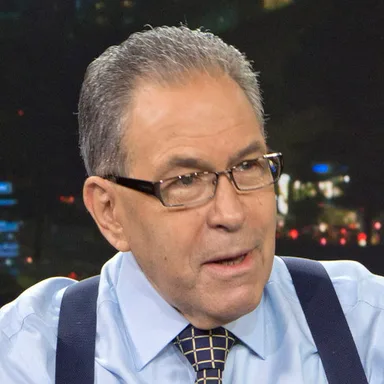
Michael Stoler Real Estate Expert
Shawn Rosenthal, Vice Chairman, Debt & Structured Finance, CBRE
Transcript
Automated transcript · uncorrectedGood morning. This is Mike Stola for the Stolen real Estate Report on the CATS round Table. Money for real estate is a big topic. Per A couple of weeks ago, I had Frank Corsokwinski, who is the senior executive vice president of the Flushing Bank, talking about money for real estate.
So today I have the guru of money for real estate. I have Sean Rosenthal, who’s the vice chairman at CBRE Capital Markets. Correct, Correct, thanks for coming here today.
Thanks for having me, Michael. We’ve known each other for a long time and it’s really a treat to do with you.
So the big question is what’s happening with the money for real estate? Since the assets are all way down in their value, let’s talk about that.
Sure way I would describe money for real estate and the capital markets, both debt and equity is I think it’s a tale of two cities. You’ve got certain asset classes still highly in demand, multifamily, industrial, data centers, self storage, retail, retail, retail, certain retail retail. Everyone wrote off retail years ago with COVID because of Amazon, retail has stood the test of time.
But I’d say that again, the first few things I mentioned specifically multifamily, specifically industrial, specifically data specifically storage highly in demand. And what you’ve seen is.
Even in New York City with multifamily.
Well, we can talk about the rent stabilization situation in a minute, because I think it really depends. I’m really talking about a national focus. And there are pockets of every asset class which are highly in demand and some that are challenged. But what’s happened is the office sector, as everyone knows, is highly not in demand. There are
certain the highest quality assets still have bids, still have people looking to lend and buy. However, just given what’s happened with rates, values have adjusted significantly. But however, on the office side, where you’ve got anything with any kind of lease up or value add or you know from you know from the fifty percent quality and lower with vacancy,
there’s no bit. I mean, we’re seeing situations across the country where assets are to office buildings are trading at twenty five cents on the dollar. I’m talking about a New York City asset that was bought by a very large sponsor in.
You’re talking about seventeen forty other day, which was written up in the article.
I’m not talking about seventeen forty, but I’m talking about an asset that was bought on the West Side for one hundred and sixty million dollars in twenty eighteen and is now Class B office building approximate two hundred and fifty thousand feet, which is under contract hard contract to sell for forty. We’re seeing assets in the Midwest, large
office buildings in Chicago which were owned for four hundred and fifty million dollars with an institutional equity three hundred million of debt, now going to sell for approximately one hundred. Okay again, so going from four hundred or four to fifty of value to one hundred, from one hundred and sixty million of value to forty, there has been a
massive shift, and we’re finally starting to see some of the institutions and some of the players starting to take a hit. And part of the reason, aside from questions about leasing, questions about how much a cost to lease up these building tenant demand, part of the issue is the financing. There’s no financing for those assets, which greatly
greatly brings down the pricing and the people who can buy it, and so it really you know, it’s a tale of two cities. Like I said, multifamily okay, around the country has been in huge demand. Things traded in twenty one twenty two at insane pricing with growth projections and models and unrealistic expectations about future growth. Those assets
are kind of working their way through, many of them over levered, and but there’s strong demand at the right price. So there’s been a price shift depending on the asset and the quality and the location and the you know, there’s been a shift in values. Okay, but there’s strong demand.
And again, the shift of money from office has to go somewhere, and so where there’s the amount of capital that was chasing office or in the office space, it was the number one I believe in terms of institutional interest that could be. I mean, I’m not one hundred percent sure of that, but massive demand for office and
that’s got to shift somewhere.
So who’s taking up for the demands? Who’s financing these buildings even at a seventy percent discount?
So it’s interesting, it’s not so simple, okay, on fifty or sixty percent least office buildings, even at these kind of discounts. You’ve got certain debt funds you’ve got private funds, you’ve got like unique capital. I mean the deals we’re seeing a lot of with the office that are actually trading, meaning the distress. Often we’ll have seller financing, and so
you know, I sit right next door to the loan sales team in my office, and they’re selling off distressed office around the country. And when they price these transactions, they’re pricing some with and without seller financing, and so on the transitional side, if you have a again less than seventy five percent less than seventy percent least asset, right,
the larger the deal, it’s extremely hard to trade because the financing gap unless they’re seller finances.
Okay, let’s talk about CNBS financing. Sure, what’s happening with that and the single asset.
Single borrower. Sure, So on the office side and otherwise, right, we were talking before about assets that are seventy percent least or sixty five percent least or less, and how the liquidity for that market is challenged on the CNBS side, across across all asset classes. Since January first through right now, the market is extremely hot, extremely on fire. It’s it’s
it’s it’s I believe, I don’t I don’t know the exact stats, but it’s I think we’ve done twice as much has been done in CNBS men last year, and a lot of it is called is Sasby financings. And I’m not sure you know there was an article as you mentioned to me today about sasby. Sasby is single asset,
single bar or financing and these are ext either large portfolios of assets. It could be a lot of industrial has been done, a lot of multifamily in lise Up were you know, maybe a multi family where Sasby or the Wall Street markets can price, can squeeze out more proceeds than Fanny or Freddy, which continued to be aggressive
on every multi family hotels. Large Sasby financings has been extremely, extremely popular, and you’re seeing the Blacksons of the world, the Brookfields of the world, the large institutional owners all running into that space regularly.
And what are you seeing with regards to New York City multi family which you’re caught by rent stabilization.
Yes, so I think there’s been as I’m sure you’ve spoken about, and everyone knows, you know, the regulations that came out in twenty nineteen has gutted the market, so six you know, values can be down anywhere from twenty five to fIF right, and you’re starting to see some of those trades. And so we’re actually working right now
in a deal in Queens. The cap rates are in the sevens for you know, nice renty family. That that’s high relative to I mean massively high relative to the low cap rates in the past. There’s a lot of bad loans on people’s books. A lot of the banks who had at originate sixty five percent loans maybe one
hundred percent LTV it’s working its way out. Signature has a bunch, you know, obviously sold the portfolio of loans. You’ve got New York Community Bank Flags start working through their issues on all these loans. The rent stabilized business is a bad business right now. And you’ve seen a lot of over the last five years. Even you’ve seen
a lot of historically family owners here in New York just go everywhere everywhere else, buying in Charlotte, in the Midwest, you know, places where they can make a return.
And what’s happening with the insurance companies they were a source.
Of I would say the insurance company market actually has come in dramatically in the last sixty days, and so insurance companies generally like to lend on high quality assets at safe leverage. In the beginning of the year, I’d say the first quarter, we worked on a couple of brand new Class A multi family assets. These happened to
be in Denver for a large client, and they were in lease up. They bought at eighty five percent least. And when we bid the financing from Fanny May and Freddie mac versus the insurance companies, Okay, Fanny May and Freddie mac on those transactions were about sixty five percent loan to cost at spreads of approximately one sixty at
that time, and at that time the life companies were one or five points less leverage and almost forty or fifty basis points more in pricing. What about gold on fast forward to right now, that’s in the first quarter, Fast forward to right now on large talking about multifamily and other assets, there’s really a dogfight for those loans
between the insurance companies and Fannie May and Freddie Mack for you know, fair leverage, you know, multi families.
What about financing for hotels?
The hotel financing is definitely available, and our hotel team is run by somebody named Lawrence brit Fan who has a spectacular track. Round has been extremely busy. Transitional hotels are financing hotels have actually many of the hotels, specifically in New York, the numbers on hotels have improved dramatically.
Part of that is also due to the migrants.
Well, you’ve also had a lot of hotels come offline in the last you know, two, three, four years, and so I think that coupled with just people coming back to the city in dramatic force. You walk around, it’s packed.
So what do you see for the next six months. How is this going to be for investment, sales and also for financing.
I think a few things. I think you’ve started to see it in the last month or so with the inflation information if data starting to suggest and I think now there’s a ninety eight percent probability that you know, the first rate cut will happen in September. You know, that’s been bouncing around and so that has I think
that’s a positive step in the right direction for rates, and so you know you’re starting to see rates come down. I mean, one of the things that’s been challenging the transaction market Aside from high rates has been the incredible volatility.
I mean meaning a buyer is underwriting a six percent rate one day, a five and a half percent rate, you know, a week later, and then maybe a six in of course, the volatility and the speed of the volatility has made it very hard and so rates coming down.
We think political right, political risk. You know, it just seems like, you know, there’s always people nervous about that. But we the cbview is that the second half is just on a call this morning, the second half will be signific, we think, significantly pick up an activity.
So you’re positive on the market, then you’re positive in New York City, no question about that. And I’d like to thank Sean Rosenthal of CBR for being here today.
Thank you very much for next week. Take care
Sunday, August 4, 2024
Mayor Adam's Choice for Corporate Counsel.
Randy Mastro Partner, Dechert LLP; Former NYC First Deputy Mayor
Report on Paris Olympics. Better to watch on TV.
Alfonse D'Amato Former U.S. Senator from New York
The Safe Hotels Act is not so safe for hotels.
American Hotel Association Pres. Kevin Carey
The assassination attempt has changed America.
Roger Stone Political Strategist & Consultant
Book: Risks and Returns: Creating Success in Business and Life.
Former Sec. of Commerce Wilbur Ross
The Fed has many tools to confront inflation.
David Malpass Former President, World Bank Group
What Cities may become too hot to live in? Climate Change.
Steve Kates Space and astronomy broadcaster (Dr. Sky)
Michael Stoler
The Stoler Report with Michael Stoler: David Schechtman
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
Michael Stoler Real Estate Expert
The Stoler Report with Michael Stoler: Eli Weiss and Andrew Albstein
Michael Stoler Real Estate Expert
